Stay Debt Free & Save Up For Purchases And Projects, from the workbench
Q: You truly should consider posting about how you two budget and save for your purchases and Hands-on. I am constantly amazed at how you seem to never charge anything and how you consistently mention saving up for things. Now simply tell us how you do it!! What about making the decision to replace something that still works? Is that a hard call for you folks? I never know when to live with something, replace it with something semi-low-cost for the interim or save up for the big thing I in fact want and go right to buying that instead of putting money towards a placeholder while I save. I’d enjoy to know more about how you know when to save and when to splurge and how you live such a debt free life full of projects and home makeovers! -Barbara
A: First and foremost, John and I are especially lucky to each come from families with famously frugal dads. So we both learned all about saving up for things, paying off our whole credit card balance, and never buying anything that we cannot afford on the day that we buy it. Of course it takes a decent amount of discipline (and it means that we are constantly walking away from strong deals & lovely things), but if we cannot afford them they are not such good deals after all. So to honor our dads, we thought we’d post embarrassing old photos of them. Notice John’s dad’s tie- it was a Father’s Day gift John made using puffy paint… proof that paint does not consistently make something better.
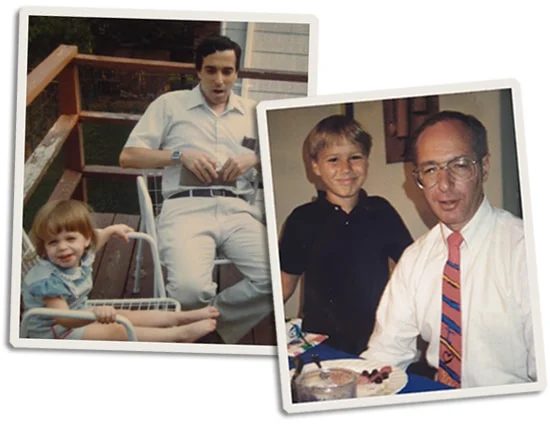
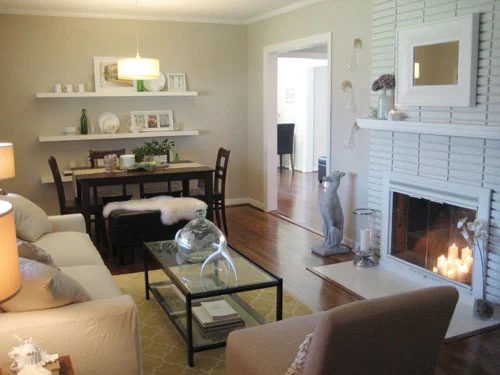
It is funny because a lot of our stuff falls into the “plain and affordable” category (our dining table was around $150 from Target and we have a $25 thrift store chair in our den and a $30 consignment shop coffee table in the living room). So that truly helps us keep money in the bank. We do not believe in buying chintzy low-quality stuff to save a swift buck, but if there is a chunky wood dining table at target.com with good reviews for a third as much as the one on potterybarn.com, we are likely to go for the thrifty Tar-jay version (we have had our current dining table over three years and have not had one complaint yet).
But although we typically shop around for the best deal (and read reviews to be sure we are not seduced by a lemon), every once in a while we do fall in love with the notion of something pricey and save for it like crazy (like our plush organic mattress or the new 2009 Altima that we saved for over the course of the past few years and then paid for in full on the day we drove it off the lot). But more on that a bit later. In short, the key to our financial approach truly is simply to hold out for sales, use coupons, shop around, and aim for affordable items to mostly fill our home- and then devote a sliver of our savings to spendy stuff here or there (so we do not feel totally deprived but also do not drain all that money that we saved up overnight either).
Oh and living in Richmond helps! The cost of living is waaaay lower than it was in Manhattan, so years of dealing with those insanely inflated expenses makes it seem a lot easier to cut costs and save money here (since our mortgage is half of what we used to pay to rent two compact NYC apartments). Our house was also fully affordable since it was a total fixer-upper (as in: less than 200K, you folks have seen the befores!). So we knew we could afford to put money towards fixing it up since we did not spend it all up front by purchasing a newly renovated casa to come home to (and since our monthly mortgage payment is a lot lower than it would have been for an already vivid new home in the area).
We also try to be frugal in other ways like by sharing a car, getting books from the library, making our own bagged lunches, and DIYing whatever we can (from tiling to haircuts) instead of paying an expert (you will see some links to other how-we-save-money posts at the bottom of this one). It is not consistently glamorous, but the old a-penny-saved-is-a-penny-earned adage truly rings true to us. So instead of making plenty of money and spending it simply as swiftly, we choose to do what we enjoy- aka: blogging- but live comfortably on less with a few plain switcheroos like haircuts at home and one dollar spaghetti dinners.
As for what we do when it comes to replacing something that works but still bothers us (like a functional old fridge that is big and yellowed and likely not terribly energy efficient) we simply save our pennies up if it truly makes us cringe. Once we have sufficient to in fact afford a new one without putting it on a credit card that we will not be able to pay off right away (which makes us feel so guilty that we would not enjoy the spurge) we go for it. Oh and we consistently sell the working thing that we will be replacing on Craigslist so we do not send it off to a landfill. Plus then we get a bit of money for it (which we can mentally put towards our upgraded version, so it feels even more affordable in the long run).
We have learned that in our case it is never smart to buy something low-cost for the interim simply to tide us over because we end up hating the fact that we spent money on something that is simply a placeholder for the real thing that we want (and we would rather have waited and put our money towards the forever-item instead of some temporary solution). This is a personal thing though, so if replacing your cringeworthy chandelier with a $50 version from Home Depot will assist tide you over while you save for the $250 beauty that you will enjoy forever, then it might be the best approach for you. Simply think about what makes you glad and what you can honestly afford and try to weigh the pros and cons to come up with a plan that feels right for your situation.
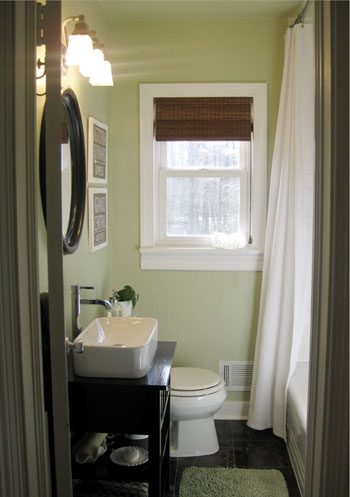
We also consistently talk a lot before taking on a major room makeover to be sure that we are both on the same page about how much we will spend. For example, after a lot of chatting and number crunching we guessed that we’d spend 3-5K on the bathroom remodel- and were totally surprised when we got it done for $1800 by doing all the labor ourselves and hunting down some remarkable deals. So in the case of the big bathroom reno, we saved our pennies until we had 5K sitting there in our high yield savings account and ended up especially glad to simply spend the 1800- which meant we could move on to our nursery makeover with extra funds already on hand… which is consistently a bonus!
We in fact find that we overestimate things a lot more frequently than we go over our budget- which we are quite thankful for- but we still like to save up all the money and make sure it is in the bank simply in case we do not come in under budget (it would be especially stressful if we only saved two thirds of what we needed for a project simply because we assumed we were overestimating again). Oh and there is a bonus to having our renovation dollars in the bank before we start. We have found that it takes a lot of stress and anxiety out of the equation, so the project is a lot more lively.
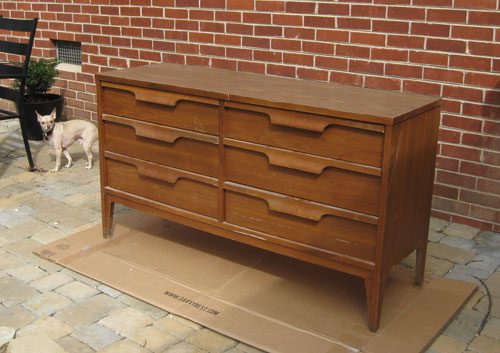
Take the nursery makeover for example, we went into it thinking that we’d spend around $1500 since we needed totally new furniture and accessories (like a crib, mattress, dresser, chair, ottoman, rug, curtains, chandelier, lamp, art, etc). But thanks to some deal hunting we have in fact done everything from scoring a $20 thrift store chair and a $20 Craigslist dresser to hunting down a clearance rug and chandelier- which makes us confident that we will get ‘er done without reaching or exceeding our budget. Who knows, we might simply come in substantially under if we are lucky. It truly does pay to spend the time pounding the pavement for the best deals and trolling places like Craigslist for solid well made furniture that you can refinish (a lot of which is much better quality than the low-cost stuff that companies churn out today). See how the Craigslist dresser below turned out after we made it over with some stain, some paint, and some elbow grease.
All told, we likely spend between five and ten percent of our total income on home improvements (not bad considering that we are fairly much constantly painting something or pulling up at Home Depot). But that is simply a rough approximation and it is a truly personal thing so each family should look at their bank account and their house to figure out what budget and home improvement priorities are the most essential to them. Plus it is kind of our job now (since I am a full time home blogger we need to constantly take on projects to sustain our site). So because it is such a high priority in our life, we go out of our way to save a lot of money in other areas, like by having simply one car that is fully paid off.
We drove a ten year old Maxima for four years with over 170,000 miles on it until we could save sufficient cash to fully pay for a safer-for-the-baby 2009 Altima, which we did a few months ago (yeah, that was a lively day). So making sacrifices and cutting costs in other areas has allowed us to save money which we use to pay things off fully (instead of continually laying out cash each month for a car payment or a credit card bill that we simply cannot squash). And of course we do save a bundle on the transportation front by making the decision to be a one car household, so we can save all the money that might otherwise go towards purchasing, insuring and gassing up a second car.
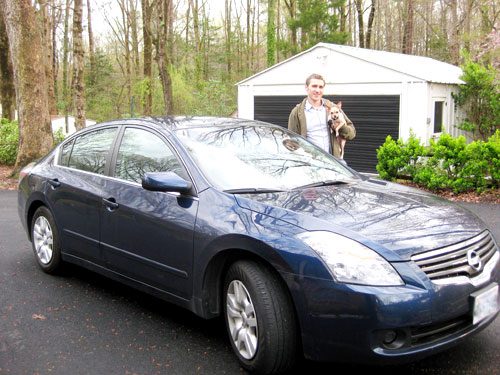
We know the way that we save and pay things off is rare. And we know that there are likely people reading this post who have no idea how on earth two people like us could save up for renos before we do them or pay off a new car the day they drive it off the lot (hint: it is not because we make a lot of money- in fact by national averages we fall way below the average income level, even in our area). So we will share this factoid about our spending habits. We are insanely frugal in many areas where other “normal” people are not. A pleasant meal out for us is a once monthly trip to Chipotle. We likely spend about $10 a month on clothing (combined, and some months it is zero). In fact I have spent less than $20 on my whole maternity wardrobe (thanks to generous friends and family members who have passed their leftovers my way). We have even begun to make our own cleaning products to save more money in that area and we already mentioned that we give each other haircuts instead of paying a professional.
So before you think it is totally impossible to save a few hundred dollars a month towards some big reno goal or some dream furnishings that you’ve had your eye on, consider whether you can cut anything out at all (from that Starbucks coffee to that monthly haircut). And if you want to save even more, try going a whole month without buying clothing or going out to eat. All of a sudden you will see that it is not that hard to save money once you truly decide to make a major change. Heck, you can even downgrade from two cars to one (and start carpooling or riding your bike). Or you can even sell your pricey vehicle for something a bit older with more miles on it (trading car glamour for house glamour is not a foreign concept to us since we drove our last car into the ground and sold it to Carmax with nearly 200,000 miles on it when we at last had sufficient saved up to replace it).
In general our advice is simply never to spend beyond your means and to take the time to save for items and projects that are truly essential to you… instead of frittering away funds by grabbing a bunch of low-cost accessories (but they are on sale!) that you do not need every time you walk into a store. Resist the urge! Truly, if we do not have the money in savings that we are talking about spending then we simply do not spend it. Instead we use paint and other items that we already have around the house for some free mini makeovers to tide us over. And we are consistently sure to take our time hunting down the best deals while our savings account grows (even doing things like hosting a garage sale or selling unnecessary items on Craigslist to make money to put towards our latest goal). And it seems to work for us- so we certainly hope that it does for you folks as well. Glad saving (and smart spending) to you and yours!
Oh and we’d enjoy to hear how you save your pennies (any envelope system peeps out there?) or how you live well on less income. Share and share alike!
Pssst- To learn more about how we pinch pennies here at Casa Petersik check out our Save It series (read Part 1 here, Part 2 here, and Part 3 here) and find even more money saving ideas right here. Oh and this post about living with less (along with this one and this one) might assist too.